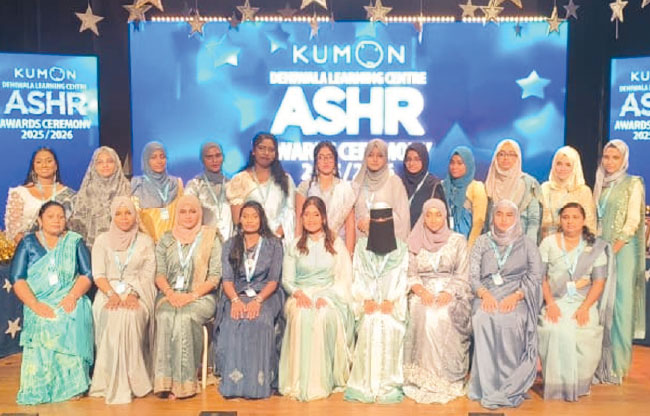
Kumon Dehiwala Learning Centre celebrated its 2026 ASHR Awards Ceremony under the theme ‘A Sky Full of Stars’ on October 31 at the Buddhist Cultural Centre in Colombo 05, honouring the achievements and academic progress of 207 young learners.
The event recognised students for their dedication, perseverance and remarkable accomplishments throughout their Kumon learning journeys, highlighting the importance of consistent effort and independent learning.
Held under the leadership of Femidah Wahid, Franchisee of Kumon Dehiwala Learning Centre, the ceremony was attended by distinguished representatives from Kumon India and Sri Lanka, including Koya Nishimura, Managing Director of Kumon India and Sri Lanka; Minu Padam, Group Leader, Kumon India and Sri Lanka; and Bhumika Vashisth, Area Development Manager, KISL South Division.
The awards recognised students who had achieved significant academic milestones, including those progressing six months, two years, three years and five years ahead of their respective school grade levels, as well as learners who had successfully completed their Kumon programmes.
Special awards were also presented to students in recognition of their exceptional effort, consistent homework completion, regular attendance and notable learning progress.
Adding to the celebrations, the programme featured captivating performances by students, inspiring presentations and a spectacular finale that brought the evening's ‘A Sky Full of Stars’ theme to life.
With more than 36 years of experience in the education sector, Femidah Wahid has been leading Kumon Dehiwala Learning Centre since its establishment in April 2014. Under her guidance, the centre has continued to expand its reach and recently recorded its highest subject enrolment in 12 years.
Wahid highlighted that the benefits of Kumon education extend well beyond academic achievements. The Kumon Method focuses on developing independent learners by nurturing confidence, self-discipline, perseverance and a lifelong enthusiasm for learning.
The ceremony also recognised the commitment and contributions of the centre's instructors, while acknowledging the invaluable support of parents, whose encouragement and involvement remain essential to each child's educational progress and success.
Seylan Bank Records Strong Q3 2026 Performance with LKR 9.1 Billion in Profit After Tax
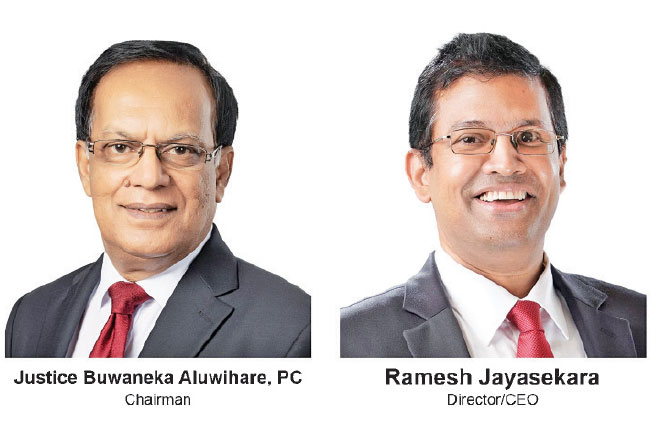
Seylan Bank has reported a strong financial performance for the nine months ended September 30, 2026, recording a Profit After Tax (PAT) of LKR 9,116 million, representing a 9.47% increase compared with the LKR 8,327 million reported during the corresponding period in 2025.
The Bank's Profit Before Tax (PBT) for the third quarter of 2026 stood at LKR 14,044 million, up from LKR 12,809 million in the corresponding quarter of the previous year, reflecting year-on-year growth of 9.64%.
Net Interest Income recorded a growth of 6.62%, reaching LKR 28,848 million for the nine-month period, compared with LKR 27,057 million in 2025. This improvement was primarily supported by the expansion of the Bank's total assets, underpinned by strong deposit mobilisation. However, the Net Interest Margin (NIM) declined from 4.50% in 2025 to 3.99% in Q3 2026, reflecting movements in market interest rates.
The Bank also recorded notable growth in net fee-based income, which increased by 18.19% to LKR 7,110 million from LKR 6,015 million in the corresponding period of 2025. The improvement was largely driven by higher fee income generated through card services, remittances, trade activities, lending and other financial services.
Total operating income increased by 8.87% to LKR 37,253 million, compared with LKR 34,218 million in the previous year. This growth was supported by improvements in net interest income, net fee and commission income, gains from the derecognition of financial assets and other operating income.
Meanwhile, total operating expenses rose by 13.54% to LKR 18,557 million for the nine months ended September 30, 2026, compared with LKR 16,343 million in the corresponding period of 2025.
Personnel expenses increased by 12.98%, from LKR 8,749 million to LKR 9,884 million, mainly reflecting annual salary revisions. Other operating expenses, including depreciation and amortisation, also increased by 14.20%, primarily due to higher costs of consumables and related services.
On the asset quality front, the Bank recorded a net impairment reversal of LKR 232 million in Q3 2026, compared with an impairment charge of LKR 645 million in Q3 2025. Its asset quality indicators remained stable, with the Impaired Loan (Stage 3) Ratio standing at 1.02% as at September 30, 2026, compared with 1.03% in December 2025. The Stage 3 Provision Coverage Ratio was recorded at 84.98%, demonstrating a strong level of provision coverage.
Income tax expenses increased by 9.96% to LKR 4,929 million for the nine-month period, compared with LKR 4,482 million in 2025. In addition, Value Added Tax on Financial Services and the Social Security Contribution Levy increased by 10.53%, rising from LKR 4,420 million to LKR 4,885 million during the period.
Kumon Dehiwala Learning Centre Honours Young Achievers at ‘A Sky Full of Stars’ ASHR Awards Ceremony